How to Fill Out the SS4 Form for an LLC?

Form SS-4 is the IRS application for an Employer Identification Number (EIN), a federal number used to identify a business for tax purposes. The form asks about the LLC, the person who controls it, and why the EIN is needed.
Form SS-4 requests an EIN; it does not choose an LLC’s federal tax classification. Read the IRS overview of Form SS-4; an eligible applicant can use the IRS’s free online EIN application instead of sending a paper form.
Quick Summary
- Form SS-4 requests an EIN; it does not elect an LLC’s tax classification.
- Line 7 identifies an individual responsible party; lines 8 and 9 cover the LLC and its federal classification.
- Default-taxed single-member and multi-member LLCs answer line 9a differently.
- Applying directly through the IRS is free; choose the method that fits your location and timing.
Form SS-4: LLC Lines to Complete
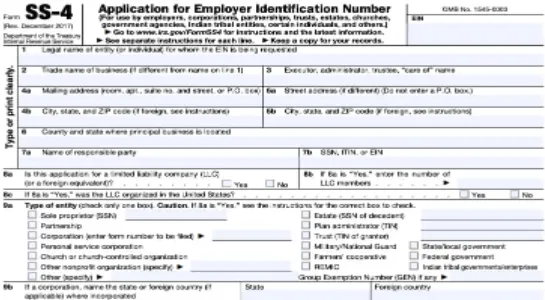
Read the current IRS line-by-line instructions [1] before completing the lines that apply to your LLC. Accurate answers help the IRS process the application without requesting missing information.
- Lines 1–2: Enter the LLC’s legal name on line 1. Use line 2 for a different trade or “doing business as” name.
- Lines 4–6: Give the mailing address, physical address if different, and the county and state of the LLC’s main physical business location.
- Lines 7a–7b: Name the responsible party and enter the requested taxpayer ID. For a nongovernment applicant, this must be an individual who ultimately owns or controls the LLC, not another entity or nominee; follow the instructions for “foreign” or “N/A” if the person has no SSN or ITIN and cannot obtain one.
- Lines 8a–8c: Identify the applicant as an LLC, report its member count, and state whether it was formed in the United States. If spouses are the LLC’s only owners in a community-property state and choose disregarded treatment, IRS instructions say to enter 1 on line 8b.
- Line 9a: Report the LLC’s federal tax classification. Use the guidance below; this answer does not make a tax election.
- Lines 10–12: State why the EIN is requested, when the business started or was acquired, and the closing month of its accounting year.
- Line 13: Enter the highest number of employees expected in each category during the next 12 months. Enter zero if none are expected.
- Lines 14–15: Line 14 lets an eligible employer request annual filing on Form 944; use that schedule only if the IRS confirms it. Enter the first wage date on line 15, or “N/A” if no employees are planned.
- Lines 16–18: Describe the main business activity and product or service, then answer whether the applicant has previously received an EIN.
An authorized person must sign and date the application. If the responsible party changes after the EIN is issued, notify the IRS on Form 8822-B within 60 days.
Related Articles:
How to Answer Line 9a for an LLC
Line 9a records the LLC’s federal tax classification, but the SS-4 is not an election. A domestic single-member LLC that accepts default disregarded-entity treatment generally checks “Other” and writes “disregarded entity”; a domestic LLC with two or more members that accepts default partnership treatment generally checks “Partnership.”
An LLC that elects C corporation treatment generally files Form 8832; an eligible LLC that elects S corporation status files Form 2553. For either election, follow the SS-4 instructions for the Corporation box and expected return type. A timely Form 2553 does not also require Form 8832 solely to elect S status.
Foreign-organized LLCs can follow different default classification rules based on ownership and member liability. Check the IRS instructions before using the domestic single-member or partnership answer [2].
When an LLC Needs an EIN
An LLC generally needs its own EIN if it has employees, owes certain federal excise taxes, or is taxed as a partnership or corporation. A domestic single-member LLC that remains a disregarded entity and has no employees or excise-tax liability generally does not need a separate EIN for federal income-tax reporting, although a bank or state may still require one. Review the IRS rules for single-member LLCs for your situation.
If you are forming the LLC, wait until the state has formed it before applying; the IRS says applying earlier can delay the EIN. Prepare the LLC’s legal name, address, responsible-party details, start date, tax year, and main activity before you begin.
Choose an IRS application method: An LLC formed in the United States or a U.S. territory, with its principal place of business there, can use the free IRS online EIN tool if its responsible party has a valid SSN or ITIN. If the LLC is ineligible or the tool is unavailable, submit Form SS-4 by fax or mail.
Applicants whose principal place of business is outside the United States generally can apply by phone, fax, or mail. Use one method per LLC and confirm current submission details on the IRS page.
Related Article:
FAQs
Does Each LLC Member Need a Separate EIN?
No. If an LLC has an EIN, it is generally assigned to the business, not separately to each member. Whether the LLC needs an EIN depends on its tax classification and employment or excise-tax obligations.
Who Enters an SSN or ITIN on Form SS-4?
For a nongovernment applicant, line 7 names an individual responsible party, not the LLC or another entity. Enter the requested SSN or ITIN, and follow the IRS instructions if the person has neither and is not eligible to obtain one.
When Should an LLC Submit Form SS-4?
Submit paper Form SS-4 when applying by fax or mail; an eligible U.S. applicant can instead use the IRS’s free online EIN application. Apply when the LLC needs an EIN, and mail the form at least 4–5 weeks before you need the number.
References:
- https://www.irs.gov/instructions/iss4
- https://www.irs.gov/publications/p3402